OPEC’s 2026 Supply Reset: Output Cuts, Gulf Risk and Market Share

The Organization of the Petroleum Exporting Countries (OPEC) has spent much of 2026 recalibrating its supply strategy, navigating a complex confluence of internal policy shifts, persistently weak global demand growth, and escalating regional supply risks. For international contractors, export managers, and trade advisors monitoring the OPEC 2026 output policy and regional supply risks , the year has been defined by a gradual unwinding of voluntary cuts, a firm commitment to a market-share defense, and the ever-present shadow of Gulf shipping disruptions affecting OPEC oil trade. This operational environment presents distinct procurement implications, particularly in logistics, maritime security, and infrastructure resilience across key Middle Eastern crude flows and OPEC production decisions.
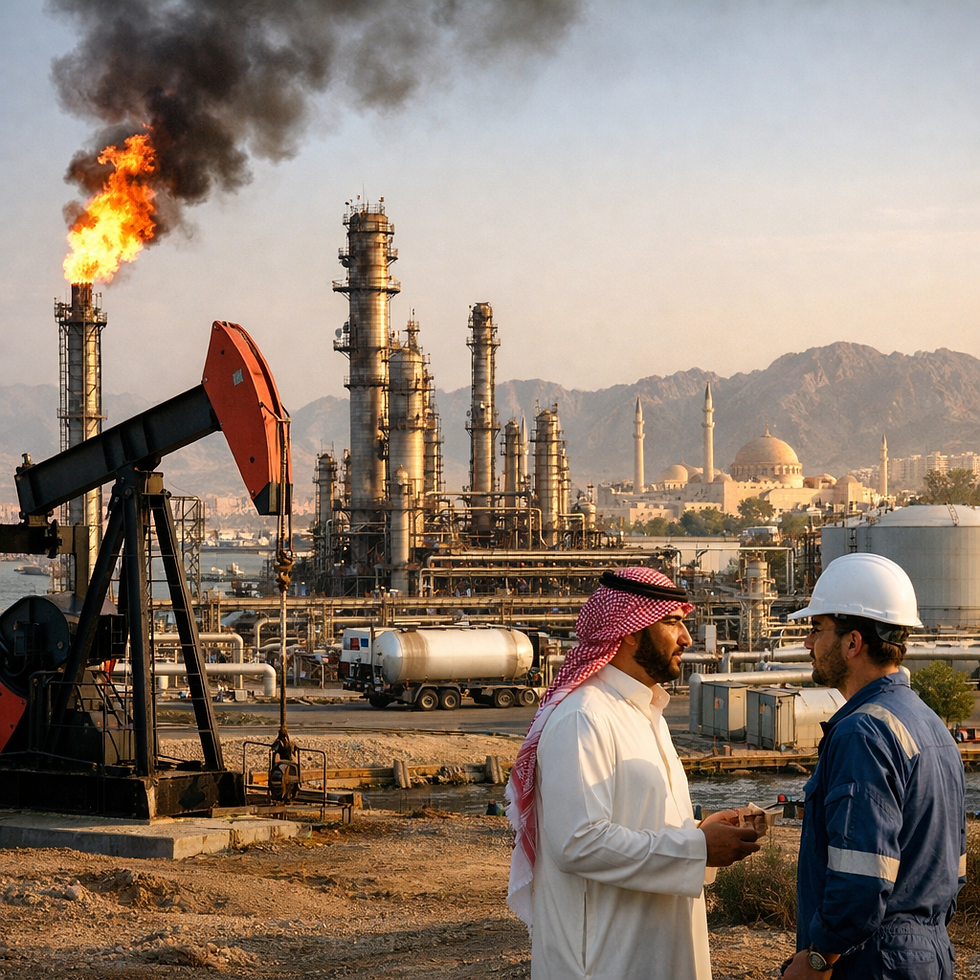
OPEC+ initiated a significant supply adjustment, moving to reverse 1.65 million b/d in voluntary cuts first implemented in 2023. By September 2026, the group approved a 188,000 b/d increase, marking the sixth consecutive monthly rise and effectively completing the rollback of those earlier voluntary reductions. However, a separate 2 million b/d cut, initially agreed in 2022, remained firmly in place through year-end 2026. This nuanced approach, as reported in October 2026, reflects a clear pivot towards a market-share strategy, with quotas raised by approximately 2.5 million b/d, representing about 2.4% of world demand. This shift impacts the volume and pricing dynamics for crude exports from major producers like Saudi Arabia, Iraq, Iran, and the UAE, influencing their procurement needs for associated services.
OPEC’s Shifting Demand Outlook and Market Share Strategy
OPEC’s 2026 demand forecasts have undergone a series of significant downward revisions, painting a picture of a global economy struggling to absorb additional crude supply. In April 2026, OPEC initially projected world oil demand growth at around 1.4 million b/d, reaching an average of 106.5 million b/d for the year, with non-OECD demand driving about 1.2 million b/d of that increase. This early optimism, however, proved unsustainable.
By September 10, 2026, Reuters reported that OPEC had lowered its 2026 oil demand growth estimate to a mere 380,000 b/d, marking the fifth consecutive downward revision. The trend continued into mid-October 2026, with Argus reporting a further cut, projecting global oil demand to grow by only 180,000 b/d, reaching 105.72 million b/d. This revised figure was confirmed by an IEF comparative analysis, which cited OPEC’s October 2026 report forecasting average 2026 oil demand at 105.7 million b/d after a 0.2 million b/d downward revision. These figures stand in stark contrast to the April projections, highlighting persistent economic headwinds and their direct impact on the OPEC demand forecast revision and market share strategy .
Despite the dwindling demand projections, OPEC's internal logic appears to be balancing this weakness against a constrained outlook for non-OPEC supply growth. October coverage indicated OPEC expected combined non-DoC liquids supply and DoC NGL production to reach 63.6 million b/d in 2026, an increase of 0.8 million b/d, primarily driven by the United States, Brazil, Argentina, and Canada. This suggests that while demand is soft, OPEC sees limited competitive pressure from other producers, reinforcing its market-share defense strategy. For procurement teams, this implies sustained, albeit adjusted, production levels from OPEC members, necessitating ongoing investment in operational maintenance, field services, and associated logistics infrastructure.
Gulf Shipping Disruptions and Regional Export Logistics
The year 2026 has been heavily influenced by significant shipping risks in the Arabian Gulf, transforming maritime transport from a routine operational cost into a critical strategic vulnerability for OPEC’s major producers. An IEA-linked analysis noted that Gulf crude exports reached 13.9 million b/d in September 2026, an increase of 4.4 million b/d, with flows through the Strait of Hormuz seeing increased reliance on ship-to-ship transfers in the Gulf of Oman. This operational adaptation underscores the severity of the threats.
However, the increased reliance on these routes came at a substantial cost. On October 12, 2026, OPEC ministers and non-OPEC partners issued a stark warning that disruptions to maritime routes were delaying shipments and fueling inflationary pressures. Market reporting from October 2026 corroborated this, detailing how shipping and insurance costs had surged to over one-third of commodity value, with tanker freight rates reaching record levels. This directly impacted crude delivery costs and eroded refinery margins for buyers, making the economics of crude trade considerably more challenging.
The Strait of Hormuz remained the primary chokepoint. An IEA analysis in September 2026 revealed that Hormuz flows averaged only 7.6 million b/d in August, a staggering 13.1 million b/d below pre-war levels. Cumulative export losses via this vital waterway were approaching 2.8 billion barrels. These disruptions to Middle East exports, compounded by reduced supply from Russia and some Asian countries, also severely impacted downstream product markets, cutting global diesel/gasoil availability by 1.7 million b/d in Q3 2026 compared to the previous year. For procurement specialists, this translates into an urgent demand for maritime security services, advanced tracking systems, alternative logistics solutions, and robust insurance packages for operations touching the Gulf region. Tenders for maritime security and logistics support are likely to remain active.
Country-Specific Exposure and Geopolitical-Energy Security
The shipping-cost shock and operational vulnerabilities are not evenly distributed across the OPEC region. The primary exposure is concentrated among the major Gulf producers: Saudi Arabia, Iraq, Iran, and the UAE. These nations are critically dependent on Gulf export routes and the transit through the Strait of Hormuz for their crude sales. For instance, Saudi Arabia’s vast oil infrastructure, while robust, faces inherent risks due to its proximity to contested waters. Iraq’s southern oil terminals, crucial for its export capacity, are similarly exposed to the costs and risks of Gulf transit.
Geopolitical tensions have exacerbated these commercial challenges. October 2026 reporting described a series of attacks and threats targeting Gulf infrastructure and shipping lanes. These incidents have reinforced fears of further, potentially severe, disruptions along one of the world’s most important energy transit routes. This environment necessitates heightened investment in energy security measures, including surveillance technologies, rapid response capabilities, and secure storage solutions. Government procurement officials in these countries are actively seeking advanced solutions to protect critical infrastructure and ensure the continuity of their export operations. International suppliers of defense systems, surveillance technology, and critical infrastructure protection services will find opportunities. Tracking tenders from Saudi Arabia and other Gulf states on TendersGo provides immediate visibility into these strategic procurement needs.
Procurement Implications: Logistics, Infrastructure, and Resilience
The confluence of OPEC’s market-share strategy, weak demand, and acute shipping risks has reshaped procurement priorities across the region. Upstream megaprojects, while always a long-term focus, have taken a backseat to immediate needs for operational resilience and cost efficiency in logistics. The record freight rates, increased dependence on ship-to-ship transfers, and persistent route disruptions directly imply a surging demand for specialized services and equipment.
International contractors should anticipate a robust market for tanker services, particularly those offering enhanced security features or flexible routing capabilities. Maritime security firms specializing in escort services, port security, and offshore asset protection will find significant opportunities in the Gulf. Demand for comprehensive insurance solutions, including war risk and political risk coverage, has similarly escalated. Port handling services, especially those capable of managing increased transshipment volumes and offering expedited turnaround times, are also critical. Furthermore, the need for advanced routing support and real-time tracking systems to optimize vessel movements and mitigate risks is paramount.
Beyond immediate maritime needs, there will be a sustained focus on strengthening land-based export infrastructure and alternative pipeline routes to reduce reliance on vulnerable sea lanes. This could include tenders for pipeline maintenance, expansion projects, and associated pumping stations and storage facilities. For instance, countries like Saudi Arabia and the UAE might explore further development of their Red Sea export terminals or expand existing pipeline networks that bypass the Strait of Hormuz. These are not merely operational adjustments but strategic investments in long-term energy security and export reliability. Opportunities in the oil and gas sector , particularly in logistics and infrastructure, are abundant.
Middle East Crude Flows and Production Decisions
The strategic decisions made by OPEC members concerning crude flows are inextricably linked to their production policies and the prevailing market conditions. The gradual unwinding of voluntary cuts, coupled with the ongoing baseline cut, reflects a delicate balancing act designed to defend market share without completely flooding a demand-constrained market. This approach means that while crude output from countries like Saudi Arabia and the UAE is increasing from earlier voluntary cut levels, it remains managed within a broader framework of supply discipline.
The key dates in 2026—April 16–17, August 2, September 10, and October 12—mark significant shifts in OPEC’s posture. The April meeting established a higher demand baseline, signaling an initial intent to increase supply. The August 2 quota hike completed the unwind of voluntary cuts, putting more crude onto the market. However, the subsequent downward revisions to demand forecasts, culminating in the 380,000 b/d estimate by September 10 and further reductions by October, illustrate the persistent struggle to align supply with actual consumption. The October 12 ministerial warning on shipping disruption further complicated the picture, adding a substantial cost and risk premium to the physical movement of crude.
For international buyers and logistics providers, understanding these Middle East crude flows and OPEC production decisions is crucial. It dictates the availability of specific crude grades, the preferred loading ports, and the associated logistical challenges. The increased reliance on ship-to-ship transfers in the Gulf of Oman, for example, points to a demand for specialized lightering services and robust offshore support vessels. These operational adaptations, driven by both policy and risk, create specific procurement needs for contractors capable of operating in complex and high-risk maritime environments.
Future Outlook: Resilience and Diversification
Looking ahead, OPEC’s strategy for 2026 and beyond will likely continue to revolve around defending market share while adapting to the realities of weaker global demand growth and persistent geopolitical risks in the Gulf. The emphasis on operational resilience and diversification of export routes will only intensify. This implies a sustained demand for infrastructure development that reduces reliance on single choke points, such as the Strait of Hormuz.
For international businesses, this environment presents a clear roadmap for engagement. Opportunities will not be limited to traditional upstream exploration and production but will extend significantly into the midstream and downstream sectors, particularly in logistics, security, and infrastructure enhancement. Companies offering innovative solutions for maritime security, data analytics for supply chain optimization, and advanced engineering for pipeline and terminal resilience will find receptive markets within the OPEC region. The ability to provide integrated solutions that address both the commercial and security dimensions of crude exports will be a key differentiator. Keeping abreast of these evolving needs through platforms like TendersGo’s AI-powered tender search will be essential for identifying and capitalizing on these strategic procurement opportunities as they emerge across the region.